Form 1099-NEC Requirements for 2026: The New $2,000 Threshold Explained

If you paid contractors in 2026, you'll file Forms 1099-NEC under a different rule than in any prior year. The federal reporting threshold rose from $600 to $2,000 for payments made after December 31, 2025. That means fewer forms for many businesses. But the change also creates new ways to get it wrong: forms filed when they aren't required, forms missed because "the threshold went up," and state rules that didn't move with the federal one.
This guide covers what changed, who still needs a 1099-NEC, what's exempt, the deadlines for 2026 forms, and how to file without penalties.
1099-NEC in 2026: the short answer
You generally must file Form 1099-NEC for 2026 if you paid $2,000 or more during the year to someone who isn't your employee (such as an independent contractor, freelancer, sole proprietor, partnership or attorney), for services performed for your business.
- Payments to most corporations, payments for merchandise, and payments made by credit card or through payment apps generally don't go on a 1099-NEC.
- Forms are due to both the contractor and the IRS by February 1, 2027, since January 31 falls on a Sunday.
- If you file 10 or more information returns in total, you must file them electronically, for example through the IRS's free IRIS portal.
What changed for 2026
The One, Big, Beautiful Bill Act raised the threshold that triggers Form 1099-NEC and most Form 1099-MISC reporting. According to the IRS, for payments made after December 31, 2025, the threshold is met when payments to one recipient total $2,000 or more during the year. Starting in 2027, the amount may be adjusted for inflation.
Three details matter in practice:
- The threshold is per recipient, per year. Add up everything you paid one contractor during 2026, not each invoice on its own.
- 2025 payments still used $600. If you're catching up on late 2025 forms, the old threshold applies.
- The form itself changed. The 2026 Form 1099-NEC adds box 1b (cash tips), box 1c (tipped occupation code) and box 1d (qualified overtime), and excess golden parachute payments move to box 3. Most small businesses will only use box 1a, nonemployee compensation, but make sure your software uses the 2026 form.
Who needs a 1099-NEC
Under the IRS instructions, you report a payment in box 1a when all four of these are true:
- You paid someone who is not your employee.
- The payment was for services performed in the course of your trade or business (personal payments don't count).
- You paid an individual, partnership or estate, or in some cases a corporation.
- Your payments to that recipient totaled $2,000 or more for the year.
The first test is about the relationship, not the payment. If the worker is actually an employee, the answer is a W-2, not a 1099. Misclassifying workers is a separate, more expensive problem than a missed form. If you aren't sure, review the IRS guidance on independent contractors and employees, or ask your advisor.
Payments that usually don't need a 1099-NEC
Payments to corporations, with an exception for attorneys
Payments to C corporations and S corporations are generally exempt from 1099-NEC reporting. The main exception is legal services: fees paid to an attorney or law firm are reportable even if the firm is a corporation. The W-9 tells you whether a contractor is a corporation, which is one more reason to collect it before you pay.
Card and payment-app payments
If you paid a contractor by credit or debit card, or through a third-party payment network, don't put those payments on a 1099-NEC. The payment processor reports them to the contractor on Form 1099-K. For payment apps and online marketplaces, the 1099-K reporting threshold returned to more than $20,000 and more than 200 transactions. Card payments are reported regardless of amount. Either way, they aren't yours to report.
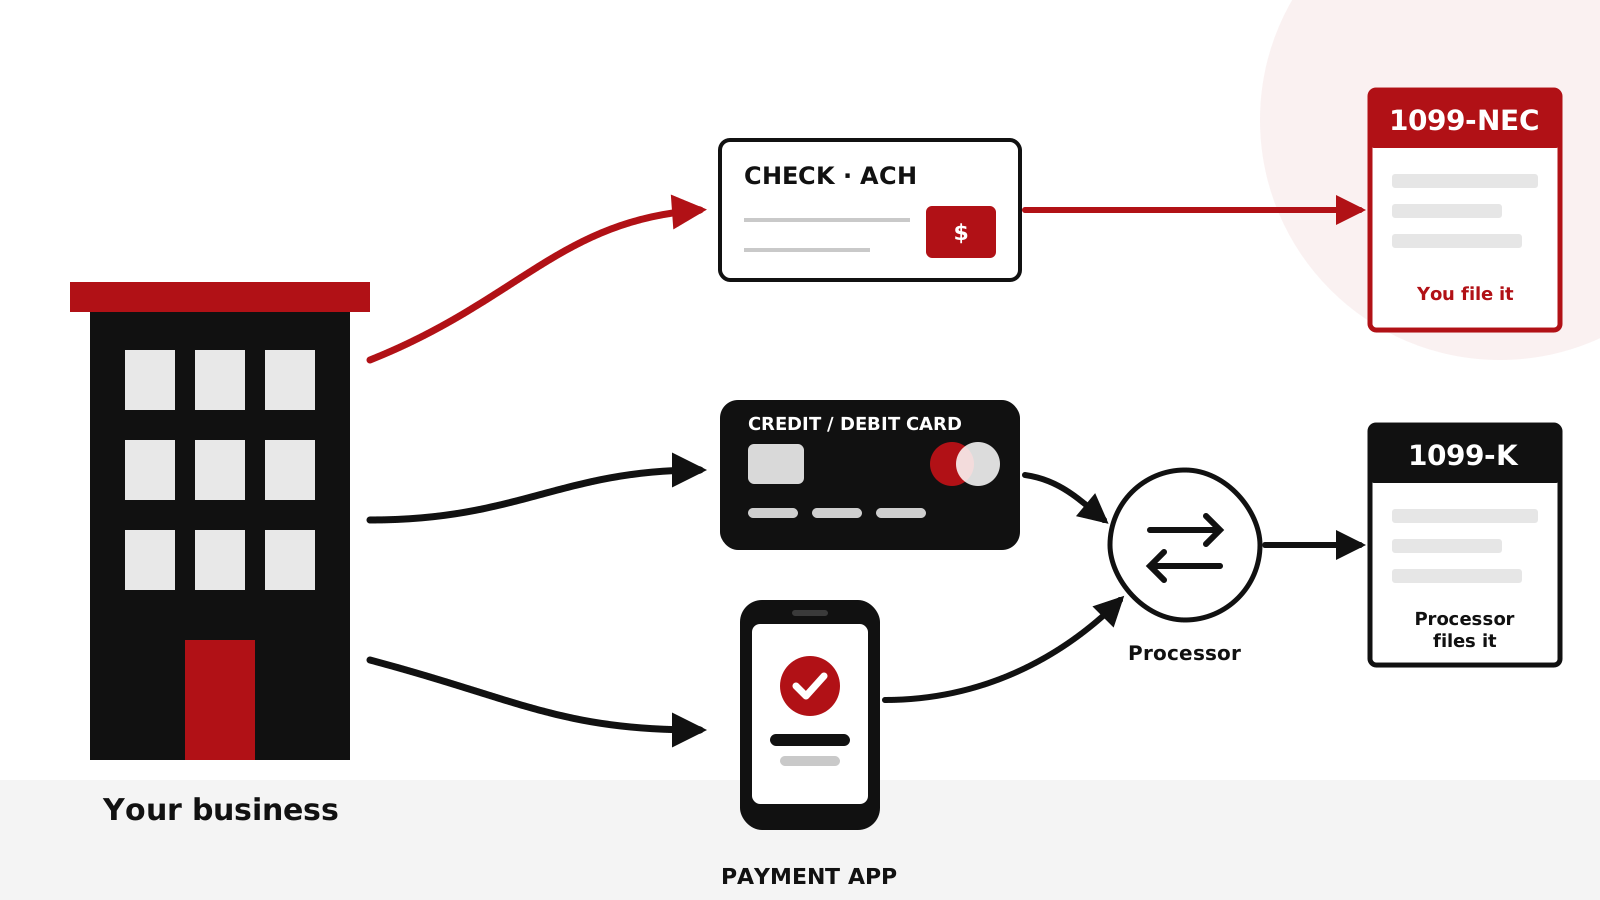
Watch mixed payment methods. If you paid one contractor partly by check and partly by card, only the check and bank-transfer payments count toward your $2,000 total.
Goods, freight and employees
Payments for merchandise, freight, storage and telephone service aren't reportable on Form 1099-NEC. Neither are wages paid to employees; those belong on Form W-2. If an invoice combines parts and labor, the services portion is what matters.
1099-NEC vs. 1099-MISC
Form 1099-NEC is for nonemployee compensation. Most other business payments that need reporting go on Form 1099-MISC. The most common split:
| Payment | Form |
|---|---|
| Contractor, freelancer or consultant fees for services | 1099-NEC, box 1a |
| Attorney fees for legal services (even to a law firm that's a corporation) | 1099-NEC, box 1a |
| Office or equipment rent paid to an individual or partnership landlord | 1099-MISC |
| Prizes and awards not paid for services | 1099-MISC |
| Gross proceeds paid to an attorney (for example, a settlement paid through a lawyer) | 1099-MISC |
| Royalties | 1099-MISC |
Collect a W-9 before the first payment
Form W-9 gives you the contractor's legal name, tax classification and taxpayer identification number (TIN). Collect it before you pay. Chasing W-9s in late January is how deadlines get missed.
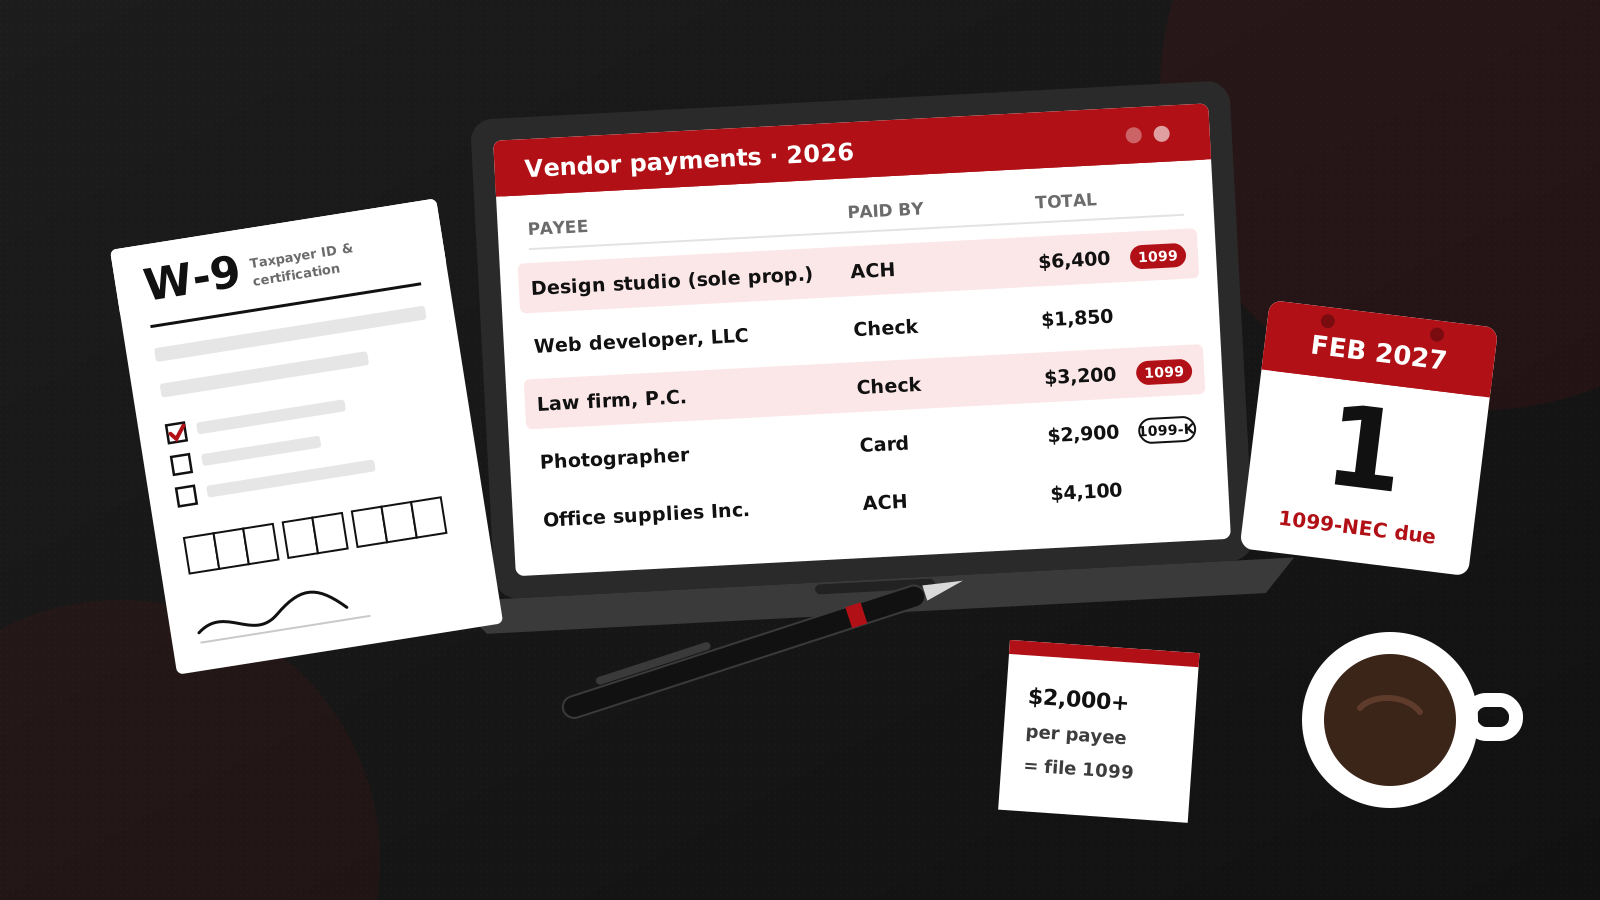
If a contractor who must be reported doesn't give you a TIN, you're generally required to begin backup withholding at 24% on reportable payments. For nonemployee compensation there's no 60-day grace period while a TIN is pending. Because the backup withholding threshold now follows the same $2,000 rule, payments below $2,000 a year generally aren't reportable and don't require backup withholding. If you withhold, report the amount in box 4 and deposit it with the IRS.
Deadlines for 2026 forms
Form 1099-NEC is due to both the recipient and the IRS by January 31, and there's no automatic extension for the IRS copy. When the date falls on a weekend or legal holiday, the next business day applies. January 31, 2027 is a Sunday, so the deadline for 2026 forms is Monday, February 1, 2027.
How to file: IRIS and the 10-return e-file rule
If you file 10 or more information returns in total (counting all types together, not each form separately), you must file electronically. Most businesses that pay a handful of contractors and employees reach that number quickly.
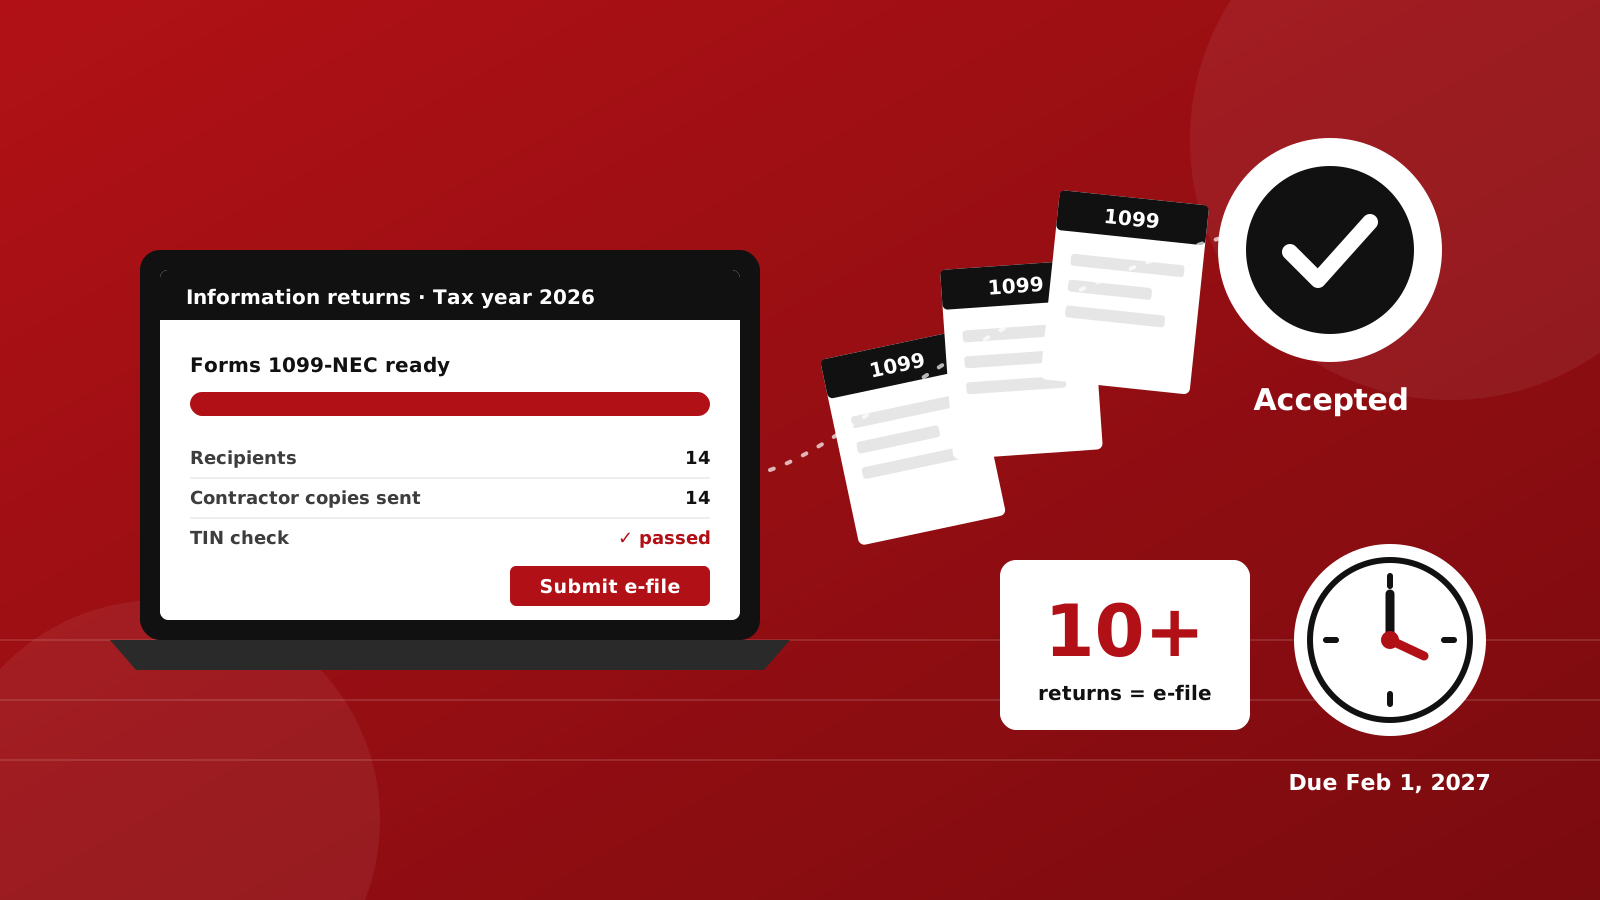
The IRS's Information Returns Intake System (IRIS) is a free online portal for filing Forms 1099 without special software. The IRS says IRIS will be the only intake system for information returns in the 2027 filing season, replacing the older FIRE system, so payroll and accounting providers are moving to it too. If you file yourself, apply for an IRIS Transmitter Control Code (TCC) well before January, because approval isn't instant.
Penalties for late or incorrect 1099s
For returns due in 2027, the IRS penalty for failing to file a correct information return on time depends on how late it is:
Those amounts are per form, and a separate penalty can apply for failing to give the contractor a correct copy. Twenty contractors forgotten until September can mean $340 for each IRS filing, plus penalties for the missed contractor copies. If you get a penalty notice, our guide on what to do when you receive an IRS notice walks through your options, and Taxulo's tax resolution team can request penalty relief when you qualify.
California rules that didn't change
For businesses in California, two state rules sit alongside the federal one:
- FTB filing. California generally receives federal 1099 information through the IRS Combined Federal/State Filing Program, so many filers don't need to file a separate copy with the Franchise Tax Board. File directly with the FTB if your California amounts differ from your federal ones.
- EDD Form DE 542. California's Employment Development Department requires a Report of Independent Contractor(s) within 20 days of paying $600 or more to a contractor, or entering into a contract for $600 or more, whichever comes first. It applies to contractors who are individuals, sole proprietors or single-member LLCs, when you're required to file a federal 1099-NEC or 1099-MISC for their services. The EDD's guidance still states the $600 amount. Confirm with the EDD or your advisor how it lines up with the new federal threshold, rather than assuming the $2,000 rule carries over. The EDD can assess $24 for each unreported contractor.
Other states have their own information-return rules. If you pay contractors in several states, review each one.
A December–January 1099 checklist
- Pull a 2026 vendor payment report from your accounting software and filter it to contractors and attorneys.
- Remove payments made by card or payment app; they're reported on Form 1099-K.
- Flag every payee at $2,000 or more, and every attorney or law firm.
- Confirm each flagged payee has a current W-9 on file, and request missing ones now.
- Check each W-9's tax classification so corporations (other than law firms) are excluded.
- Confirm your filing method: IRIS, accounting software or your payroll provider, with an IRIS TCC if needed.
- For California payees, check that DE 542 reports were filed during the year.
- Send contractor copies and file with the IRS by February 1, 2027.
The reconciliation is easier when the books are already clean. If contractor payments are mixed into "miscellaneous" or personal accounts, start with our bookkeeping cleanup checklist, or let Taxulo's bookkeeping team handle year-end vendor reporting for you.
Frequently asked questions
What is the 1099-NEC threshold for 2026?
For payments made after December 31, 2025, you generally file Form 1099-NEC when you pay a recipient $2,000 or more during the year. The threshold was $600 for 2025 and earlier payments and may be adjusted for inflation starting in 2027.
When are 2026 Forms 1099-NEC due?
They're due to the recipient and the IRS by January 31. Because January 31, 2027 falls on a Sunday, the deadline for 2026 forms is Monday, February 1, 2027.
Do I send a 1099-NEC to an LLC?
It depends on how the LLC is taxed. A single-member LLC taxed as a sole proprietorship, or an LLC taxed as a partnership, generally gets a 1099-NEC if the other tests are met. An LLC that elected to be taxed as an S or C corporation generally does not, unless the payment was for legal services. The contractor's Form W-9 shows the classification.
Do I need a 1099-NEC for contractors I paid through PayPal, Venmo or a credit card?
No. Payments made by card or through a third-party payment network are reported by the payment processor on Form 1099-K, so you don't report them on Form 1099-NEC.
Do I have to file 1099s electronically?
Yes, if you file 10 or more information returns of any type in total for the year. The IRS's IRIS portal is free and is the IRS's only intake system for information returns in the 2027 filing season.
Make 1099 season the easy part of year-end
Taxulo's CPA-led team reconciles your contractor payments, collects missing W-9s, files your 1099s on time and keeps your books ready for tax season.
Schedule a consultation with Taxulo or call 855-4-TAXULO · see our business tax preparation servicesThis article provides general information and is not tax, legal or accounting advice for your specific situation. Rules change and depend on your facts. Consult a qualified professional before acting.
Sources
- IRS: Instructions for Forms 1099-MISC and 1099-NEC (Rev. December 2026)
- IRS: Form 1099-NEC & Independent Contractors FAQs
- IRS: Publication 1099 (2026), General Instructions for Certain Information Returns
- IRS: E-file information returns and IRIS
- IRS: Publication 1220 (Rev. 5-2026)
- IRS: Form 1099-K FAQs: General information
- IRS: Backup withholding and Instructions for the Requester of Form W-9
- IRS: Information return penalties
- California FTB: Guide to information returns filed with California
- California EDD: Independent contractor reporting (DE 542)